
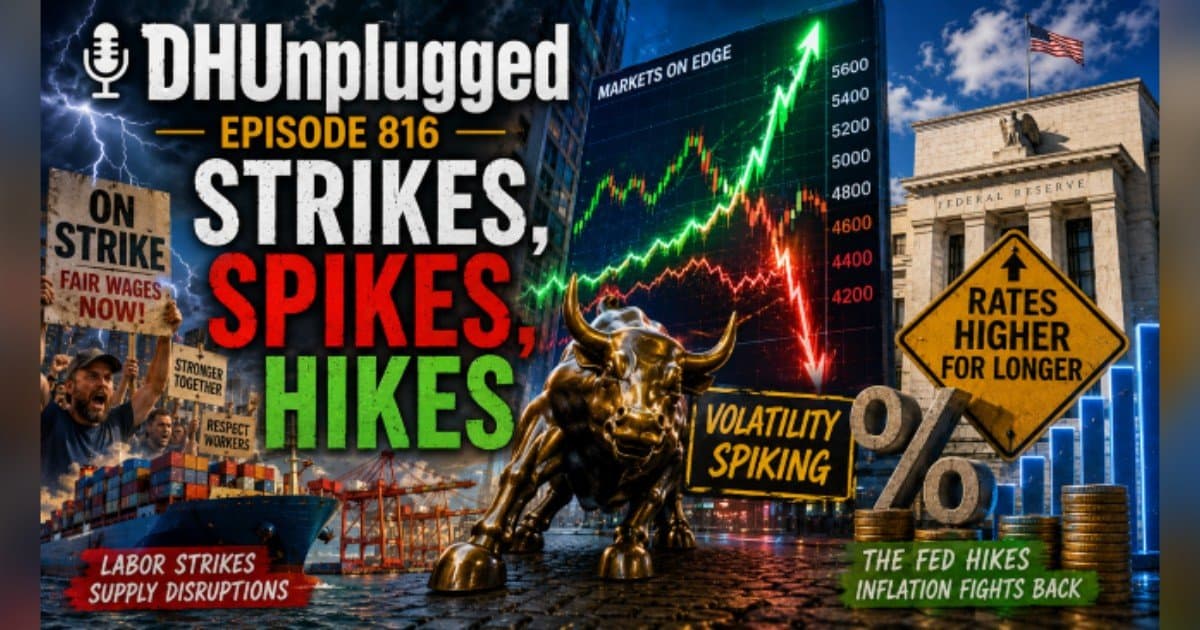
September is historically a volatile month for markets, and this year is shaping up to be no exception. In Episode 816 of the podcast DH Unplugged, hosts Andrew Horowitz and John C. Dvorak dissect the forces rattling investors: a sharp spike in crude oil, rising bond yields, and a growing lack of trust in government and financial institutions. The episode, titled "Strikes, Spikes, Hikes," was published on September 1, 2026, and sets the stage for what could be a turbulent fourth quarter.
Crude oil has surged roughly 13% in two weeks to about $91.80 per barrel, driven by renewed U.S. bombing of Iran. This spike is not just a headline number; it carries inflationary warnings, particularly through diesel crack spreads, which are flashing red. For businesses, higher energy costs could translate into increased operational expenses and pressure on margins. Consumers may feel the pinch at the pump, potentially dampening spending just as the holiday season approaches.
Meanwhile, bond yields are climbing, and Horowitz points to Treasury Secretary Scott Bessent and Fed nominee Kevin Warsh as key figures in a narrative of market manipulation. "The administration is the boy who cried wolf right now," Horowitz says, adding that "Bessent has really gotten a little bit crazed trying to manipulate the markets." Dvorak ties this to a broader erosion of trust, noting that currencies, equities, and even private valuations ultimately rest on confidence. He warns that tariff escalation reminiscent of the Smoot-Hawley Act would signal that America no longer believes it can compete on a global stage.
The episode also highlights a wave of corporate news. Dell provided blowout guidance, projecting fiscal 2027 EPS near $25.50 versus $18.99 previously, thanks to a 40% data center market share. This is a positive signal for the tech sector, particularly for companies tied to AI infrastructure. However, Nvidia's reported $12.9 billion pursuit of Hugging Face and the fallout between Jensen Huang and Sam Altman add intrigue to the AI landscape. On the retail front, Dick's Sporting Goods plunged roughly 30% as Foot Locker comps fell 3.6%, and Target faced backlash over a Halloween clown costume, highlighting the pitfalls of brand management in a socially conscious era.
The hosts also delve into government equity stakes in Intel, MP Materials, and Trilogy Metals, questioning the legality and fairness of such arrangements. Horowitz, who discloses a personal short position in Intel, wonders why Washington gets discounted shares that retail investors never see. Dvorak contrasts this with China's state-owned enterprise model and flags GLM 5.3 Flash, a Chinese AI model reportedly trained without a single Nvidia chip, underscoring the competitive threat to U.S. tech dominance.
Political tensions are high, with President Trump threatening that Iran will be "totally wiped out as a country" if it retaliates again. This geopolitical risk adds another layer of uncertainty to markets. Meanwhile, LEGO posted a 21% first-half revenue jump, and the baseball-card "casino economy" is drawing scrutiny from Japanese regulators, indicating that speculative bubbles are being watched globally.
Looking ahead, the hosts preview key economic data due Friday: August payrolls, ADP, JOLTS, and ISM reports. These will provide crucial insights into the labor market and economic health, potentially influencing the Fed's next moves. For investors and business leaders, the episode underscores the importance of navigating a complex environment where oil prices, bond yields, and institutional trust are all in flux. Understanding these dynamics is essential for making informed decisions in the months ahead.
